
Bitcoin Was Never Meant to Be Wrapped
Crypto has found ways to put almost every major asset to work. ETH can back a loan, stablecoins can earn interest, and staked assets can be traded, borrowed against, or deployed across a range of financial strategies. Entire lending markets have developed around tokens that are far smaller and less widely held than Bitcoin.
Bitcoin, however, has remained relatively difficult to use in the same way. It is still the largest asset in crypto and one of the most widely held, appearing in 68% of surveyed crypto portfolios and held by 74% of American crypto owners. Yet holders who want liquidity without selling their BTC have historically had limited options.
The industry’s solution was to move BTC away from Bitcoin’s native network and into ecosystems that developers considered better suited for building financial applications. Wrapped BTC made it possible to use Bitcoin across other chains, opening access to lending, trading, collateral markets, and other DeFi applications that were difficult to build around native BTC.
That approach solved one problem, but introduced others in its place. Using wrapped BTC meant relying on infrastructure outside Bitcoin itself and, more importantly, giving up direct access to many of the properties that make BTC such a strong financial asset in the first place: its liquidity, its global market depth, and its ability to be used as BTC itself rather than as a wrapped representation of it.
The difference between wrapped BTC and native BTC is therefore not just technical. It changes what holders are actually trusting, what asset they are using, and where the financial activity ultimately lives.
The Asset DeFi Left Behind
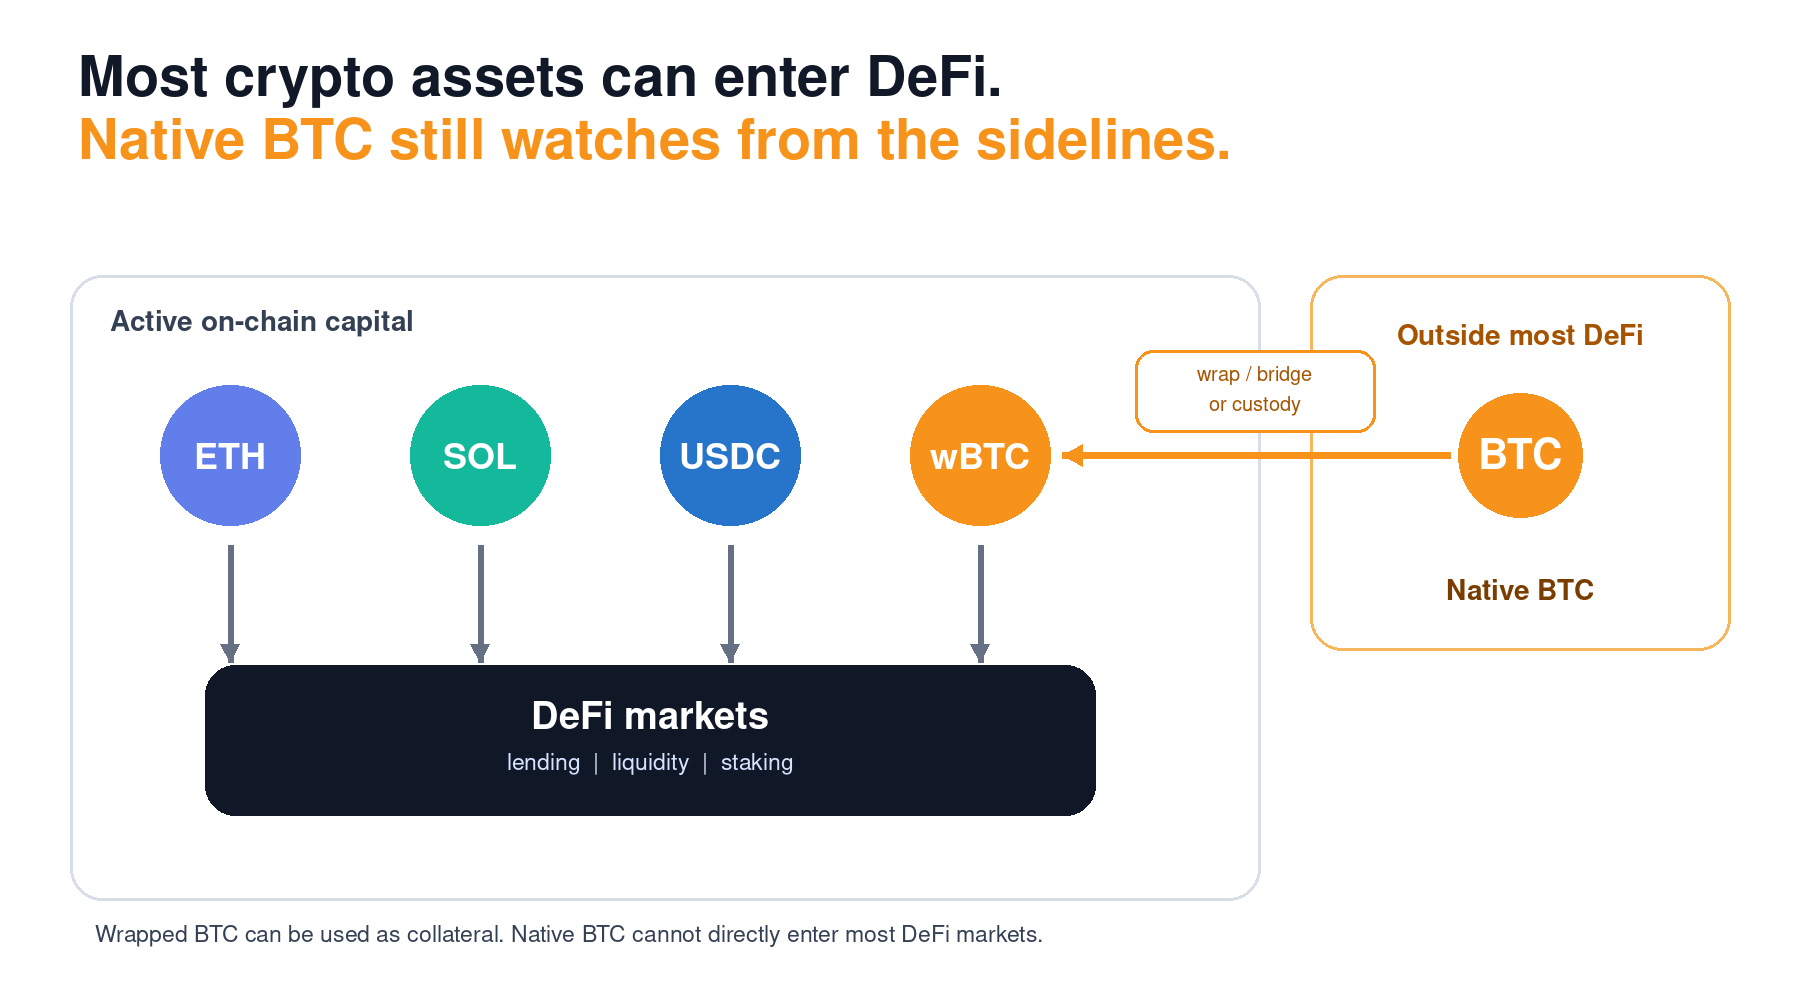
DeFi on Ethereum and Solana grew around assets that could remain within their native ecosystems. ETH and SOL became collateral in lending markets, liquidity in exchanges and capital in financial strategies without being moved onto unrelated chains.
Bitcoin followed a different path. Its base layer was built to secure ownership and transfer BTC, not run the complex applications that emerged elsewhere in crypto. Holders who wanted to use BTC in DeFi were left with a workaround: lock the bitcoin through a custodian or bridge, then receive a token representing it on another network.
Bitcoin had to leave Bitcoin to become financially useful.
Wrapping made that possible, and for years it was the only practical route into DeFi. It also meant that applications never interacted with the underlying BTC. They interacted with a separate token governed by another network, another security model and a separate redemption process.
If ETH and SOL can support financial markets within their own ecosystems, BTC should be able to do the same without first becoming something else.
Where Wrapping Breaks Down
Most of the time, that tradeoff is easy to ignore. A wrapped bitcoin token is designed to follow the price of BTC, and holders can usually move between the two without much friction. From the outside, it can feel like bitcoin with a different ticker.
The distinction matters most when either the market or the system behind the token comes under pressure.
Native BTC is secured and transferred by the Bitcoin network. A wrapped token also depends on the system responsible for holding the underlying BTC and honoring redemptions, and that dependency can break down in a few recurring ways:
- The custodian may restrict access or change hands. In 2024, BitGo announced it would move WBTC custody into a joint venture with BiT Global, an entity tied to Tron founder Justin Sun. MakerDAO responded by cutting WBTC's loan-to-value ratio to zero rather than accept the new structure.
- Signers may become unavailable. When Multichain's CEO was detained by Chinese police in 2023, the team lost access to the servers controlling the bridge, freezing user funds.
- The entity backing the token may fail. renBTC's backing unraveled in 2022 when its sole backer, Alameda Research, collapsed alongside FTX, forcing holders to rush to redeem before support disappeared.
- A smart contract may contain a vulnerability. Bridge exploits including Ronin ($624 million), Wormhole ($326 million), and Nomad ($190 million) rank among the largest losses in the industry's history.
The long-tail risk is harder to see because the token can continue displaying the price of bitcoin even as the market underneath it begins to weaken. During normal conditions, arbitrage, redemption and spot liquidity keep wrapped BTC trading close to BTC. Lending protocols accept it as collateral on the assumption that an unhealthy position can be liquidated, sold into stablecoins and closed at a profit.
That assumption becomes less reliable when many positions are liquidated at once. Liquidators receive the same wrapped asset and head toward the same spot markets, creating heavy sell pressure precisely when liquidity is disappearing. The protocol may still display a price close to BTC, but the price available for a large sale can be much lower once slippage is included.
Consider a liquidation designed to leave a 2% profit margin. If selling the collateral produces 8% slippage, the transaction loses money. Rational liquidators step away, unhealthy loans remain open and losses can turn into bad debt. A lending market cannot safely grow beyond the amount of collateral it can sell during its worst trading conditions. This is why lending risk frameworks often size markets around executable liquidity rather than headline market value. Aave’s tBTC assessment, for example, tied its recommended supply cap to the amount of collateral that could be sold before slippage reached the liquidation penalty.
Custody failures and liquidity failures arrive differently, but they expose the same weakness. A holder can lose access to the underlying bitcoin, or discover that the wrapped token cannot be sold near the price shown on screen. In both cases, the wrapper becomes the most important part of the position at exactly the wrong time.
Wrapped BTC still deserves credit. It gave bitcoin holders their first meaningful route into DeFi and proved there was demand for BTC-based financial products. The problem is that a useful workaround gradually became the standard.
That standard is a poor fit for many long-term holders. They bought BTC partly because its ownership rules do not depend on a company, issuer, or protocol treasury. Asking them to hand control to another system before they can borrow, lend, or trade has kept much of Bitcoin’s capital outside financial markets.
What Native BTC Can Enable
Once BTC no longer has to become another token, the opportunity extends beyond removing custody and redemption risk. Financial markets can begin forming around the underlying asset itself rather than separate representations spread across different networks.
The gap between Bitcoin’s size and its financial activity remains enormous. Bitcoin represents roughly 57% of the total crypto market, yet fewer than 100,000 BTC sit across the BTCFi ecosystem. That is a small fraction of the roughly 20 million BTC in circulation. Crypto’s largest asset is still one of its least financially active.
Credit is the most immediate opportunity. A long-term holder may need liquidity without wanting to sell. A business may want to use part of its BTC treasury as working capital, while miners regularly face equipment, energy and operating expenses. Borrowing against BTC allows them to meet those needs without closing the underlying position.
A functioning credit market also creates a clear source of return for lenders. Borrowers pay for access to capital, lenders earn interest and BTC secures the loan. The same foundation can support BTC-backed stablecoins, allowing holders to access dollar-denominated liquidity while keeping their underlying position. Treasury products and structured strategies can develop around these markets, with returns tied to borrower demand, trading fees and identifiable risks.
The challenge is building a lending market that can survive the conditions created from wrapping BTC. A market is only as large as the amount of collateral it can reliably sell when loans become unhealthy. October 10 showed how quickly apparently sufficient liquidity can disappear once volatility, forced selling and liquidations arrive together. Native BTC does not eliminate that risk. What it changes is the foundation on which the market is built.
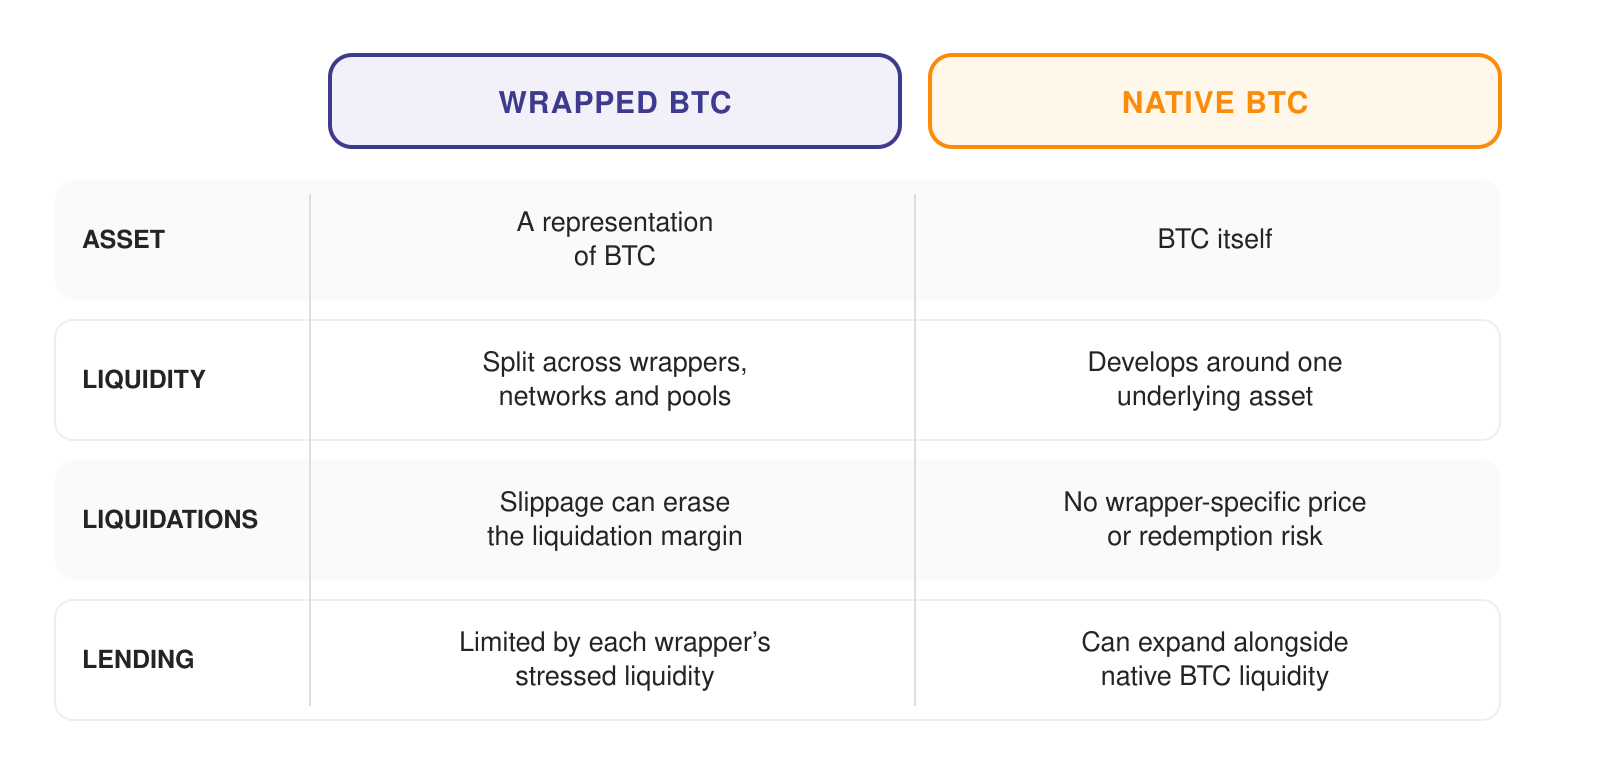
With wrapped BTC, lenders are underwriting more than the price of bitcoin. They must also consider the custodian, bridge or signer set, smart contracts, redemption process and liquidity available for that particular representation. Each dependency introduces another way for collateral to become difficult to recover or sell during a crisis. Those risks may force lending protocols to maintain lower supply caps, use more conservative loan-to-value ratios or charge borrowers more for access to capital.
Liquidity is also divided between different versions of the same asset. WBTC, tBTC and other representations trade through their own pools, networks and counterparties. Even when they all track bitcoin during normal conditions, the liquidity supporting one wrapper cannot necessarily absorb liquidations from another. The lending capacity of each market is therefore limited by the stressed liquidity of its particular representation rather than the broader market for BTC.
Arch allows lending, trading and BTC-backed assets to develop around native BTC within the same execution environment. A liquidator is not left holding a representation that must be sold through a wrapper-specific pool or redeemed through a separate system. The collateral remains bitcoin, removing the additional custody, pricing and redemption risks that lenders would otherwise need to account for.
This gives the lending market more room to grow. Trading activity attracts liquidity providers. That liquidity gives liquidators greater capacity to sell collateral when positions become unhealthy. More dependable liquidations reduce the probability that losses turn into bad debt, giving lenders greater confidence to supply capital. As executable liquidity deepens, lending protocols can support more collateral without allowing credit to grow beyond the markets protecting it.
The benefits extend to borrowers as well. They can access capital without first converting their BTC into another asset or accepting a separate redemption dependency. Removing those steps does not automatically make loans cheaper or collateral requirements lower, but it removes risks that would otherwise need to be reflected in lending terms.
The markets also reinforce one another. Borrowing creates demand for stablecoins and trading. Trading produces fees that attract additional liquidity. Deeper liquidity improves liquidation execution, which strengthens the credit market and allows more lenders to participate. A BTC-backed stablecoin can circulate through the same markets, creating further demand for borrowing and swaps.
Building this around native BTC creates a technical challenge. Bitcoin was designed to secure ownership and settle transfers, while financial applications need to update prices, balances and collateral positions continuously. Arch handles that execution without requiring BTC to move onto another chain.
A holder begins with a Bitcoin wallet and authorizes an action such as depositing collateral. The ArchVM processes the application logic, and Arch validators agree on the outcome before collectively authorizing the corresponding Bitcoin transaction. Settlement occurs on Bitcoin, and no wrapped asset is minted.
The validator network uses stake-weighted consensus and distributed threshold signing to coordinate these transactions. Moving the underlying BTC requires 51% or more of Arch consensus, preventing any single validator from moving it independently.
BTC also gives these markets an anchor whose value exists outside Arch. Its price does not depend on the success of the lending application, trading venue or stablecoin built around it. Arch can develop financial infrastructure around an asset that already has global demand, broad ownership and deep liquidity across the wider market.
This is the difference between placing a lending product on top of a wrapped token and building a financial market around native BTC. One is constrained by the liquidity and reliability of an intermediary asset. The other allows credit, trading and liquidity to grow around the underlying bitcoin itself.
Learn more about truely native Bitcoin infrastructure at: docs.arch.network